What are they leaving?
Pay may be part of it. So may the workload, the manager, the lack of a future, or the feeling that no one notices their work.
You don’t have to settle for the usual answers. A problem with your people, your cash flow, or your own future may have more than one cause—and more than one way forward.
Start with a real example: why good employees leave—and what to ask before you spend more to keep them.
Losing a good employee can cost far more than one salary. GOALL estimates turnover can cost anywhere from six months to two years of that employee’s annual pay. The usual answer is to pay more. That may be the right move—but first, ask what is actually causing people to leave and what staying would mean to them.
Pay may be part of it. So may the workload, the manager, the lack of a future, or the feeling that no one notices their work.
Different people value flexibility, recognition, security, growth, and benefits differently. Guessing can be expensive.
An answer has to work for the employees and the business. Look at cost, cash flow, and the people you most need to keep.
The point is to understand the problem before paying for an answer. That is how I approach decisions about people, protection, and the future of a business.
These business owners describe their experience with the GOALL benefits program.
“We had 100% participation! Everyone came to us and said how grateful they were that we had instituted this program.”
“One of our focuses as a growing business was to provide cutting-edge benefits in order to recruit the best employees and in order to retain great employees.”
“It just made financial sense. If you’re a business owner and you don’t have these things set up I would suggest you look into this.”
“We wanted to give our employees something that would give them the light at the end of the tunnel, so when they retire there is actually something there.”
Their experiences show what is possible. The right design for another company depends on its people, budget, and goals.
That is the question at the center of our first conversation.
This is not a sales presentation, and I will not begin by showing you a product. I begin by learning about you and the business you have built.
We’ll look at what the problem is costing—in money, time, opportunity, people, or sleep. We’ll talk about who depends on the business, who has a stake in what happens next, and how decisions about employees, taxes, protection, cash flow, succession, and your personal future affect one another.
Sometimes the answer will fall directly within my work. Sometimes it will require another professional with specialized expertise. Being helpful does not mean pretending to do everything myself. It means understanding the problem well enough to recognize what kind of help it requires—and bringing the right people to the table.
Tell me what is happening, what you have tried, and what a better outcome would make possible. We’ll look at the connections—to your people, costs, protection, and plans for the future—and identify a sensible next step.
For employers considering a new benefits approach, a complimentary company analysis may help us test whether an idea is practical before you commit to it.
Explore ideas for your people, your business, and what comes next.
Explore business solutions ›
Businesses are made of people. Whether you own one, work for one, or are planning your next chapter, we help you think through income, protection, and the people who depend on you.
Explore your options ›From taking an industrial technology into international markets to building an art gallery that connected emerging artists with buyers, I’ve learned that a good idea needs the right people, story, structure, and timing.
Today I bring that perspective to business owners. I ask what is working, what is missing, and which assumptions deserve another look.
A little more about me ›
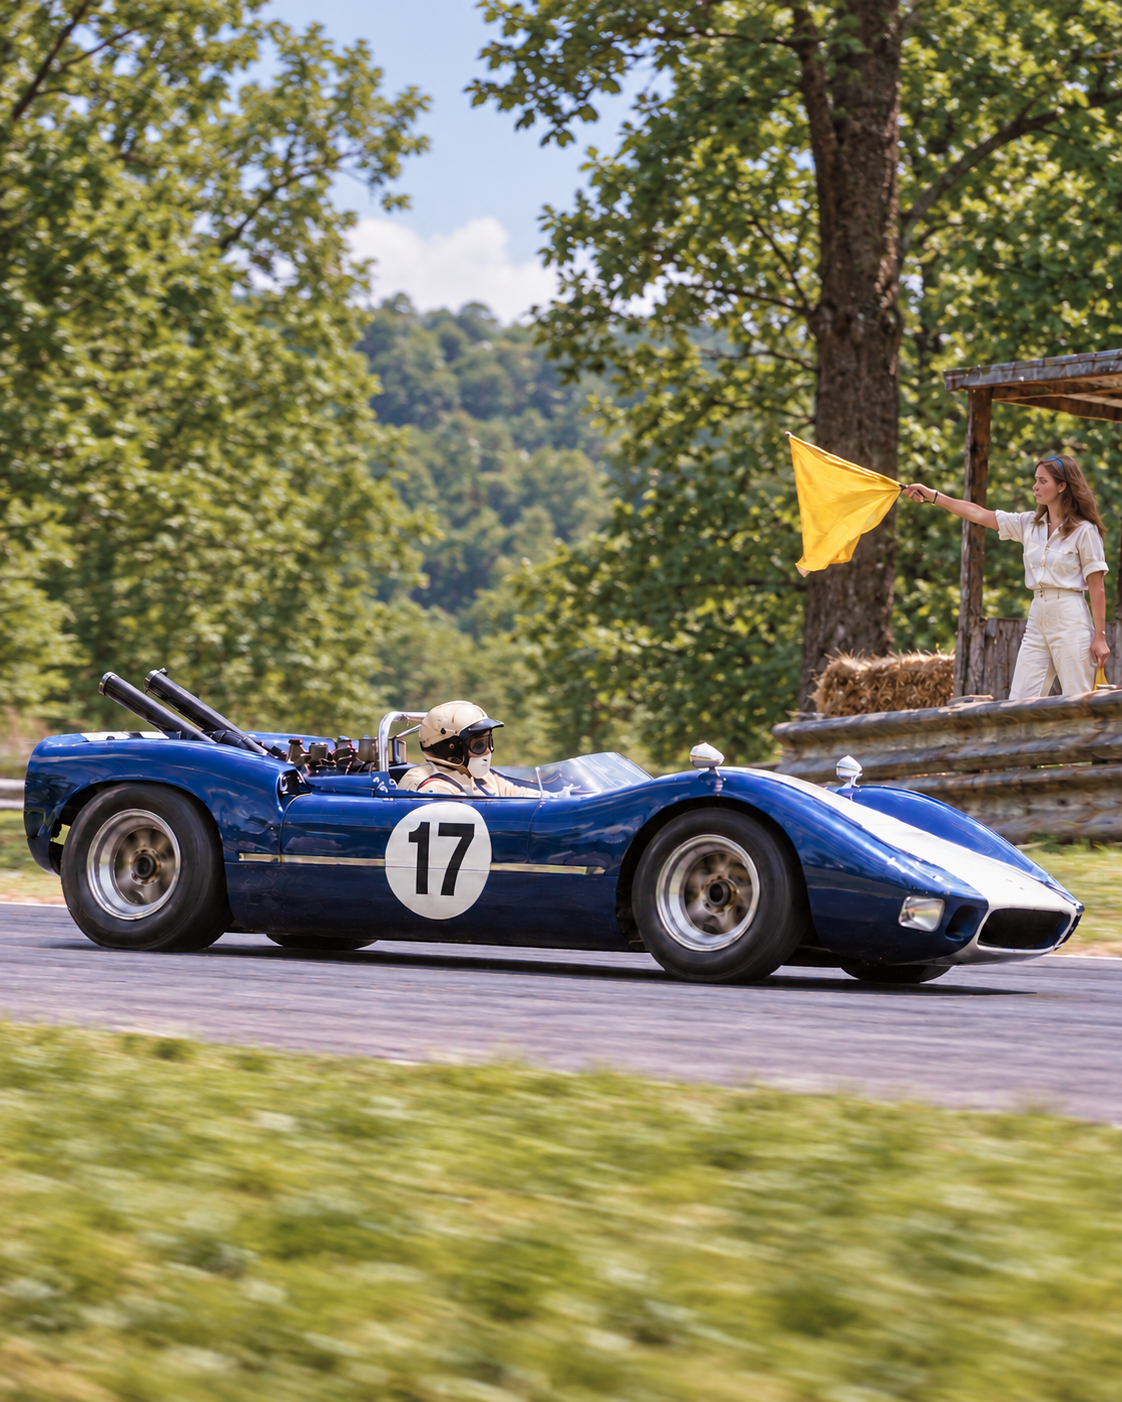
I spent years on the SCCA circuit as a safety official. I put out fires, helped rescue drivers from damaged cars, and developed deep friendships with many people in racing.
Then, on a perfectly ordinary Saturday afternoon, one of my closest friends had a catastrophic accident. Something failed on his car near the end of the straightaway. The car flipped, and he was paralyzed from the neck down. He later received what we called a “breathing pacemaker”—an implanted system that stimulated his diaphragm.
That day did not teach me to live fearfully. It taught me to live fully while preparing responsibly for what none of us expects.
Life insurance and other forms of protection cannot prevent tragedy. But they can help prevent a personal tragedy from immediately becoming a financial one for the family, employees, partners, or business left to carry on.
Trust begins with knowing what kind of conversation you are walking into.
No. I am an independent insurance professional and small-business consultant.
I do not begin by asking how much money you have available to invest. I begin by asking what problem you need to solve. When a question requires investment, legal, accounting, health-insurance, or other specialized advice, I work with the appropriate professional.
No. I am going to try to understand the biggest problem in your business and determine how I can help.
Insurance may turn out to be part of the answer. If it is, I have access to specialized products and strategies that are not offered by most brokers, and I will explain why I believe they deserve consideration. I will not force an insurance solution onto a problem it cannot solve.
There is no charge for our initial conversation.
If we determine that an insurance strategy is appropriate and you decide to proceed, I am generally compensated by the insurance company. If your problem requires another professional, that person will explain any fees or compensation before you agree to work together.
You will always understand how I—and anyone I bring into the conversation—may be paid before you make a decision.
I do not personally sell or manage employer health-insurance plans, but the conversation does not end there.
I work with specialists who understand innovative approaches to business health-insurance costs. If health insurance is the problem, I can bring the appropriate expertise into the conversation.
I work with small-business owners. That is my expertise.
The business is rarely separate from the owner’s life. Decisions about employees, taxes, protection, cash flow, succession, and retirement tend to affect one another—even when the professionals advising the business treat them as separate subjects.
Yes. I will work alongside your existing CPA, attorney, financial advisor, benefits professional, or other trusted professionals. I can also bring in specialized expertise when a problem falls outside my own work.
The goal is not for me to control every part of the solution. The goal is to help you solve the problem.
I will tell you.
If I know someone better equipped to help, I will try to connect you. And if neither I nor anyone in my professional circle can solve the problem, we will still have had a wonderful conversation—and hopefully, we will both have made a new friend.