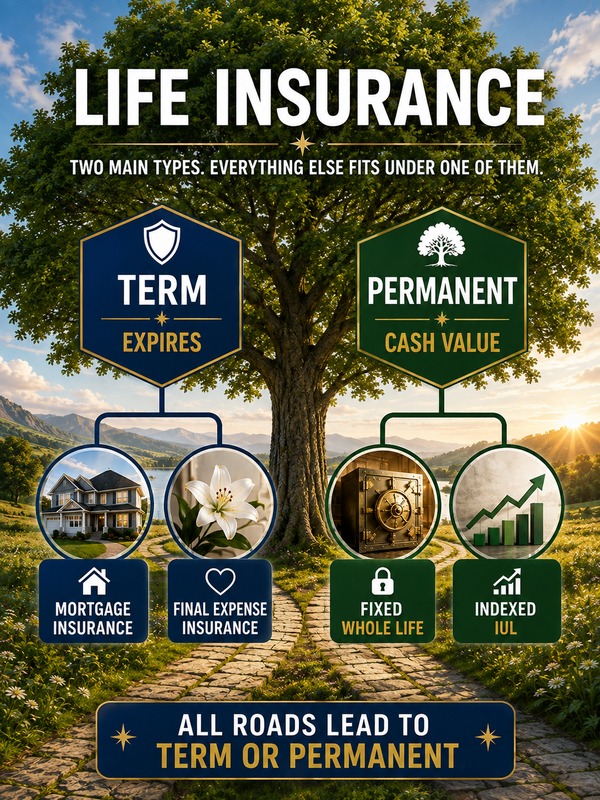
Life insurance sounds complicated because the industry has accumulated a small dictionary of names: term, mortgage protection, final expense, whole life, universal life, indexed universal life and more.
There is a simpler place to start.
Temporary coverage: term insurance
Term insurance provides coverage for a stated period or under stated term provisions. It is generally designed for death-benefit protection rather than cash accumulation.
Mortgage protection life insurance is usually not a mysterious third species. It is commonly term life insurance intended to cover a mortgage-related need. The policy structure and beneficiary arrangement can vary, so read the actual contract.
Final expense insurance describes the purpose and typical face amount more than a unique legal category. Many final-expense policies are small permanent whole life policies designed to remain in force for life if premiums are paid, though products vary.
Permanent coverage
Permanent life insurance is designed to remain in force beyond a limited term when policy requirements are met and generally includes a cash-value component.
Whole life typically offers fixed premiums, guaranteed cash values and a guaranteed death benefit under the contract.
Universal life provides more flexible policy mechanics. Indexed universal life (IUL) is a form of universal life in which credited interest is linked to the performance of an external index under the policy’s formula. It is not direct ownership of the index.
Start with the job, not the label
Do you need inexpensive protection for twenty years? Lifetime death-benefit protection? Cash accumulation? Business protection? Estate liquidity? Potential living access? Different jobs call for different designs.
There are more than literally two legal product types, but term versus permanent is the cleanest first fork in the road. Once you know which side of the tree you are on, the other labels make much more sense.