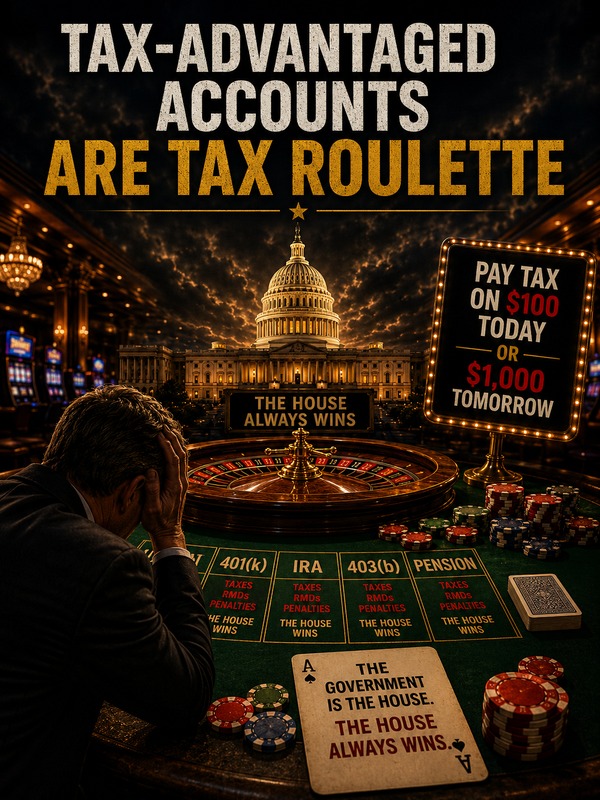
The tile is intentionally provocative. Tax-advantaged accounts really do have tax advantages. A traditional 401(k), for example, can defer federal income tax and allow tax-deferred growth.
The roulette is not whether the tax advantage exists. The roulette is what the future tax bill will be.
You know today’s rules. You don’t know tomorrow’s.
When you defer tax, you postpone the calculation. Your future withdrawals may occur under different tax rates, different deductions, different Medicare premium thresholds and different rules than the ones in effect when you made the contribution.
That does not make tax deferral bad. It makes it incomplete as a strategy if every retirement dollar is placed in the same tax bucket.
The house does not literally set your return
Unlike a casino, the government does not take a percentage of your investment gains simply because an account grew. Taxation depends on the account, contribution type, distributions, basis and tax law.
But Congress does write the tax rules. That means future tax policy is a variable you cannot personally control.
Stop betting everything on one outcome
Tax diversification can mean holding money in accounts with different tax treatments: taxable, tax-deferred and potentially tax-free. The appropriate mix depends on your current bracket, expected future income, age, time horizon and goals.
The objective is not to guess the exact tax rate twenty years from now. It is to build enough flexibility that you do not have to be right.
Sources: IRS: RMDs and IRS: IRAs.