Tax-deferred retirement accounts can be excellent savings tools. But there is one phrase I wish people would stop skipping over: tax deferred.
Deferred does not mean forgiven. It means the tax is postponed.
The bargain you made
With many traditional retirement arrangements, money can go in before current federal income tax, grow without annual tax on the account’s internal earnings, and then generally become taxable when distributed. The IRS also requires many retirement account owners to begin required minimum distributions at the applicable age. For many people today, that age is 73.
That can be a perfectly reasonable bargain. The problem is treating it as though the future tax bill does not exist.
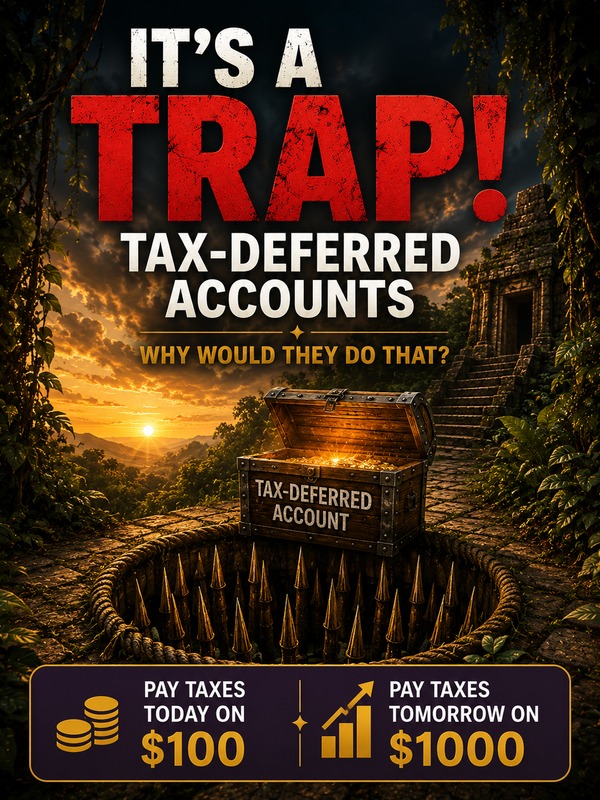
$100 today or $1,000 tomorrow?
The numbers on the tile are an illustration, not a prediction. Nobody can promise that $100 becomes $1,000, and nobody knows what your future tax rate will be. The question is about which pile of money gets taxed.
If you receive a deduction on a contribution today and the account grows substantially, future taxable distributions may be much larger than the original contribution. Whether that ultimately costs more or less depends on contribution deductions, future returns, withdrawal amounts, tax law and your tax bracket at the time.
The real trap is having no tax strategy
The answer is not automatically “never use a 401(k)” or “convert everything to Roth.” Employer matches, current tax brackets, cash flow, age and future income all matter.
But retirement planning should include a tax conversation: How much money is tax-deferred? How much is Roth? How much can be accessed under other tax rules? What happens when RMDs begin? Could withdrawals affect the taxation of Social Security or income-related Medicare premiums?
A retirement account statement shows the account balance. It does not show how much of that balance you will ultimately get to spend.
Sources: IRS guidance explains that RMDs are generally included in taxable income except for basis or amounts that can be received tax-free. See IRS: Required Minimum Distributions.