A 401(k) can do something very well: help you accumulate money for retirement. Employer matching can make it even more valuable.
But owning a 401(k) is not the same thing as having a complete retirement plan.
The questions begin when the paycheck stops
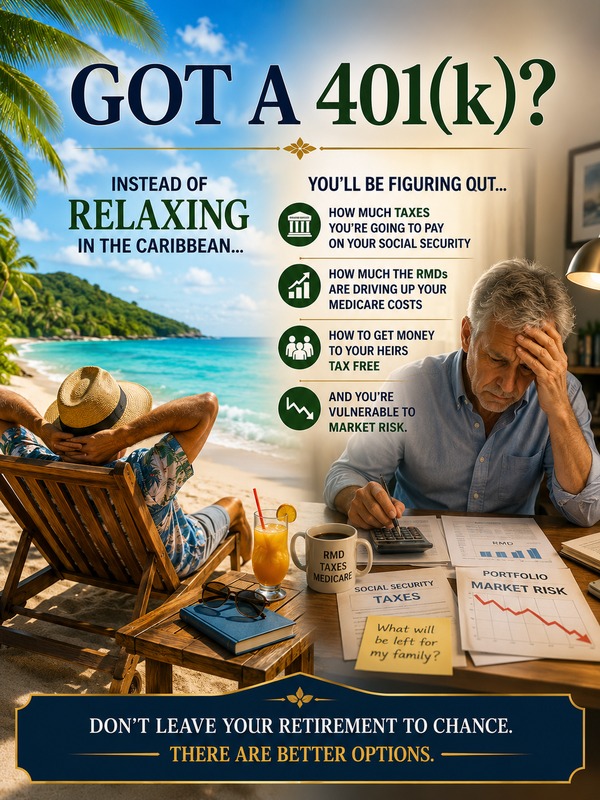
Once retirement arrives, you have to decide how much to withdraw, from which account, in what order and with what tax consequences. Traditional 401(k) distributions are generally taxable, and RMD rules eventually require distributions for many account owners.
Those withdrawals can interact with other parts of retirement. The taxable portion of Social Security depends on your other income and benefits. Higher modified adjusted gross income can also result in higher Medicare Part B and Part D premiums through IRMAA.
That means a withdrawal decision can be more than a withdrawal decision.
Then there is market risk
If your 401(k) is invested in the market, its value can fall. That may be manageable while you are accumulating. It can be more difficult when you are simultaneously taking retirement income.
And eventually, legacy
Traditional retirement accounts left to heirs can carry income-tax consequences. Life insurance death benefits, by contrast, are generally received income-tax free, subject to exceptions. Roth accounts have their own beneficiary rules.
The point is not that a 401(k) is bad. The point is that it has a specific job. It is an account, not an entire retirement strategy.
A complete plan asks: What is my reliable income? What is exposed to market loss? What will be taxable? How could RMDs affect me? What happens to a surviving spouse? What do my heirs receive? What if I need long-term care?
If the answer to all of those questions is “I have a 401(k),” there may be some planning left to do.
Sources: IRS: RMDs; IRS: Taxation of Social Security Benefits; Medicare: Costs.