I recently spoke with a business owner who plans to retire in about five years, at age 67. When we talked about retirement, she had a plan: sell the business for $200,000.
There was just one problem.
Nobody has agreed to buy it.
That doesn't mean the business isn't worth $200,000. It might be worth more. But until there is a willing buyer, at the right time, with the money and desire to purchase it, that $200,000 isn't money she can spend in retirement.
It's an expectation.
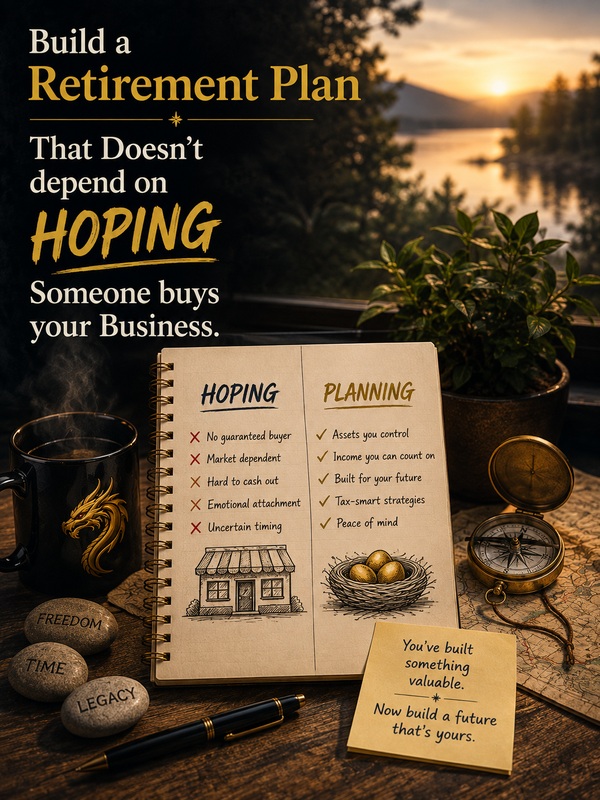
And an expectation is not the same thing as a retirement plan.
Your Business Can Be Valuable Without Being Liquid
Business owners understandably attach value to what they've built. They remember the years of work, the customers they acquired, the reputation they developed, the employees they trained and the income the company produced.
A prospective buyer looks at the business differently.
A buyer may care about revenue and profit, recurring customers, contracts, assets and liabilities, customer concentration, competition, systems, employees and how dependent the company is on the current owner.
That last question can be uncomfortable.
If the business can't function without you, a buyer may not be purchasing a business. They may be purchasing your job.
What Does $200,000 Actually Mean in Retirement?
Let's assume everything works perfectly. Five years from now there is a buyer, and the business sells for exactly $200,000.
Before considering taxes, inflation or investment returns, simply spreading $200,000 over 25 years works out to about $8,000 per year, or roughly $667 per month.
That's useful money. But for most people, it isn't enough to carry a retirement.
Investment returns could improve the arithmetic. Taxes and inflation could move it the other way. Social Security, pensions and other assets may also contribute. The point isn't that $200,000 has no value.
The point is that a sale price and a retirement-income plan are two different things.
And What If the Sale Doesn't Happen on Schedule?
Retirement dates are plans. Businesses and markets don't always cooperate with them.
What if the business is worth less than expected when you're ready to sell? What if qualified buyers are scarce? What if financing is difficult? What if a major customer leaves? What if you become ill at 64 instead of retiring at 67?
Or what if you simply discover that the company you've spent decades building isn't as easy to sell as you assumed?
If virtually all of your retirement wealth is trapped inside the business, every one of those events can become a retirement problem too.
The Better Strategy: Build Retirement Assets You Control
The goal isn't to remove the business from your retirement plan. The goal is to stop making the business carry the entire plan.
While the company is profitable and you're still working, consider deliberately moving some of the value you're creating into assets that exist independently of the eventual sale of the company.
Depending on your circumstances, that might include qualified retirement accounts, Roth accounts, taxable investments, cash reserves, real estate, or properly designed permanent life insurance intended to provide protection and potential access to accumulated policy value.
These tools don't all work the same way. That's precisely the point.
Different assets can give you different sources of future income, different tax characteristics and different kinds of control.
Let the Business Help Build the Plan
Business owners may also have planning opportunities that employees don't.
Depending on the business structure and individual circumstances, an owner may be able to use qualified retirement plans and other employer-sponsored strategies to accumulate assets for the future. Certain businesses may also consider selective benefit arrangements, such as executive bonus strategies, when appropriate.
The objective isn't to find one magical account.
It's to use the profitable years of the business to create retirement resources that don't depend entirely on what an unknown buyer may decide your company is worth someday.
Make the Business More Sellable, Too
Building assets outside the company doesn't mean giving up on a future sale. In fact, retirement planning and exit planning should work together.
A business that can operate without the owner, has documented systems, stable employees, diversified customers and reliable financial records may be more attractive to a buyer than one whose value disappears when the owner walks out the door.
So there are really two jobs:
Build a business someone will want to buy.
And build a retirement that doesn't collapse if they don't.
Hope Is Not a Financial Strategy
Your business may eventually sell for exactly what you expect. Perhaps it will sell for much more.
Wonderful.
Then the proceeds can become another valuable piece of the retirement you've already built.
But there's a profound difference between saying:
“I hope someone buys my business for $200,000 when I'm ready to retire.”
and saying:
“I'm building retirement assets I control now, and if I sell the business later, that's another asset working in my favor.”
One depends on finding the right buyer at the right time.
The other gives you choices.
After spending decades building your business, your retirement should give you more choices—not fewer.